
Introduction
In the dynamic world of real estate investment, ensuring a smooth transition from purchasing to rehabilitation and finally to refinancing is paramount. One key aspect that investors often overlook is the importance of maintaining the same Limited Liability Company (LLC) throughout these stages.
This article explores why the LLC that acquires a rehab property should be the same entity that refinances it, and why consistent entity name and ownership are now a critical lender requirement rather than a preference.
Understanding LLC Continuity in Real Estate
LLC continuity refers to using one uninterrupted legal entity for the entire lifecycle of a real estate project—acquisition, renovation, stabilization, and refinancing.
Maintaining continuity:
- Reduces underwriting friction
- Simplifies lender review
- Avoids legal and tax complications
- Aligns with modern lender risk models
Illustration 1: LLC Continuity Lifecycle
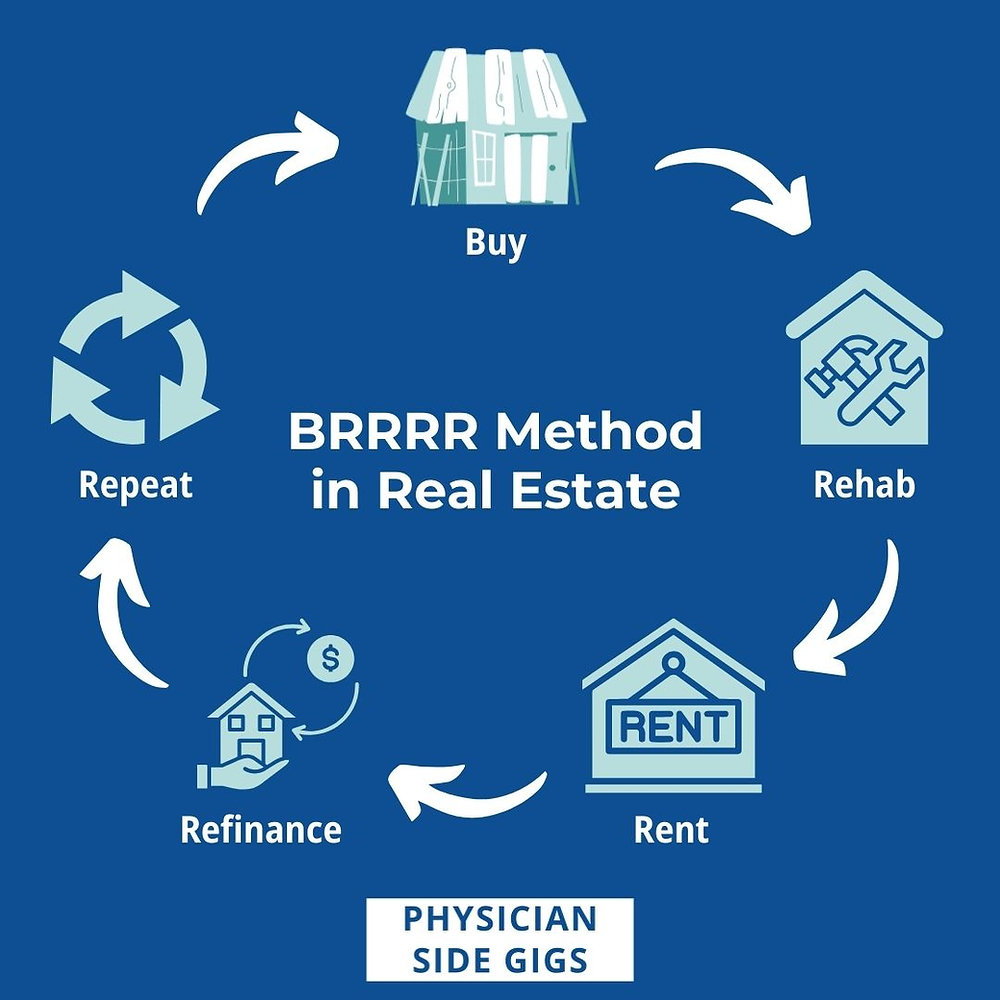
Acquisition Phase
During acquisition, the LLC:
- Takes title to the property
- Signs loan documents
- Assumes all contractual and legal obligations
Using a single, purpose-built LLC at this stage allows investors to isolate liability and establish a clean ownership record that lenders will later rely on during refinance underwriting.
Rehabilitation Phase
The same LLC should:
- Contract with contractors and vendors
- Manage renovation budgets
- Receive rehab draws (if applicable)
Keeping rehab activity inside the original LLC ensures financial continuity, consistent insurance coverage, and a clean paper trail—key elements lenders evaluate when approving refinance exits.
Refinancing Phase
Refinancing is where LLC continuity becomes non-negotiable.
Lenders underwriting DSCR or cash-out refinances expect:
- The borrower entity on title to match the original purchaser
- No unapproved transfers or entity changes
- Identical ownership percentages
Changing entities mid-stream often triggers:
- Loan denial
- Title seasoning resets
- Legal review delays
- Forced quitclaim deeds (which many lenders now reject)
The Case for Consistency: Why Entity Name and Ownership Matter
1. Lender Trust and Familiarity
Lenders price risk partly on borrower history. A consistent LLC:
- Shows operational discipline
- Simplifies risk assessment
- Can lead to faster approvals and better terms
2. Simplified Documentation
A single LLC eliminates the need for:
- Entity transfer explanations
- Additional operating agreements
- Legal opinions on ownership changes
Less documentation = fewer underwriting conditions.
3. Legal and Tax Implications
Entity changes can unintentionally trigger:
- Transfer taxes
- Re-assessment events
- Due-on-sale clause violations
LLC continuity keeps tax and legal treatment clean and predictable.
4. Reduced Administrative Complexity
Multiple LLCs multiply:
- Accounting work
- Insurance policies
- Compliance requirements
One LLC = streamlined operations and fewer failure points.
2026 Lender Trends: Clamping Down on Entity Changes
Lenders heading into 2026 are tightening controls around entity changes, especially on BRRRR and DSCR refinances.
Red flags now include:
- Title vesting changes
- Membership interest transfers
- Newly formed refinance entities
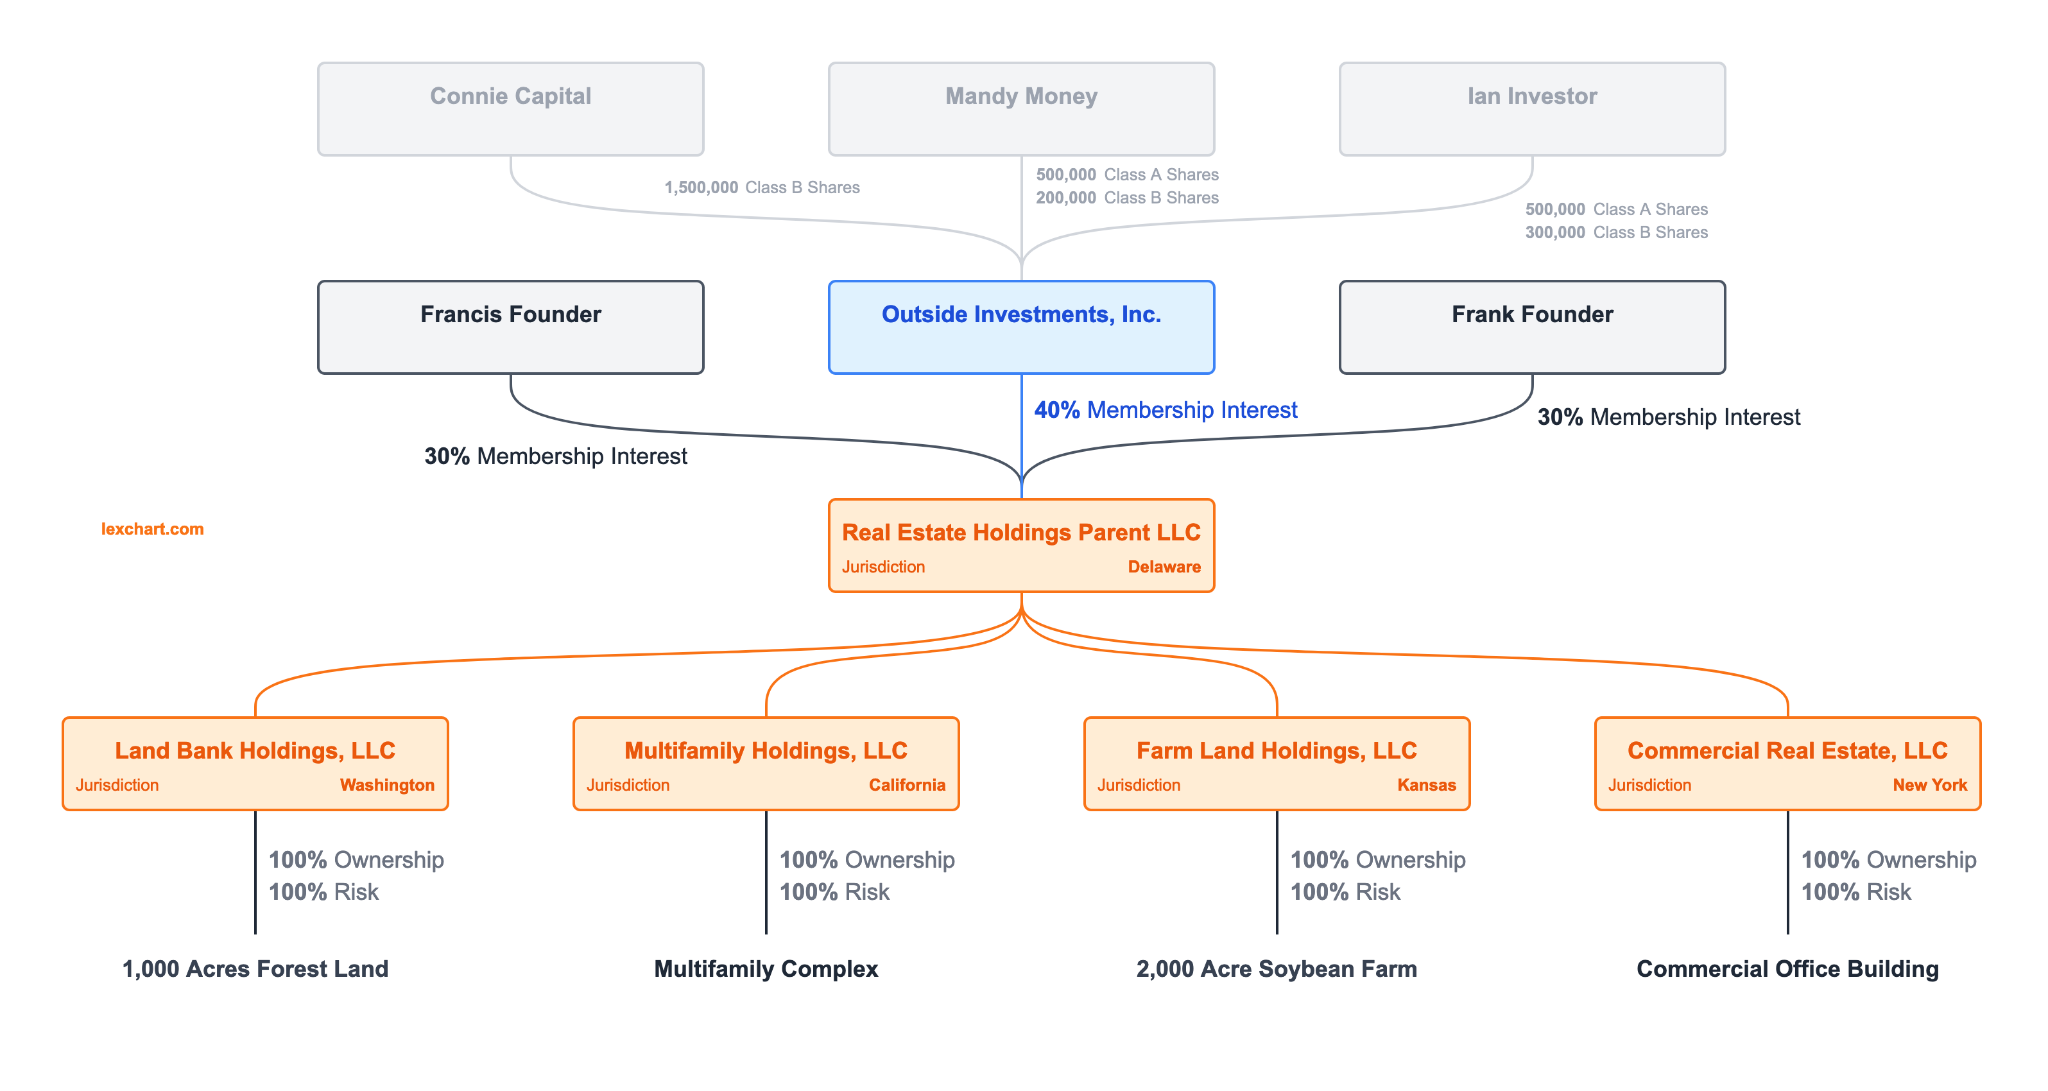
Illustration 2: Lender Scrutiny on Entity Changes
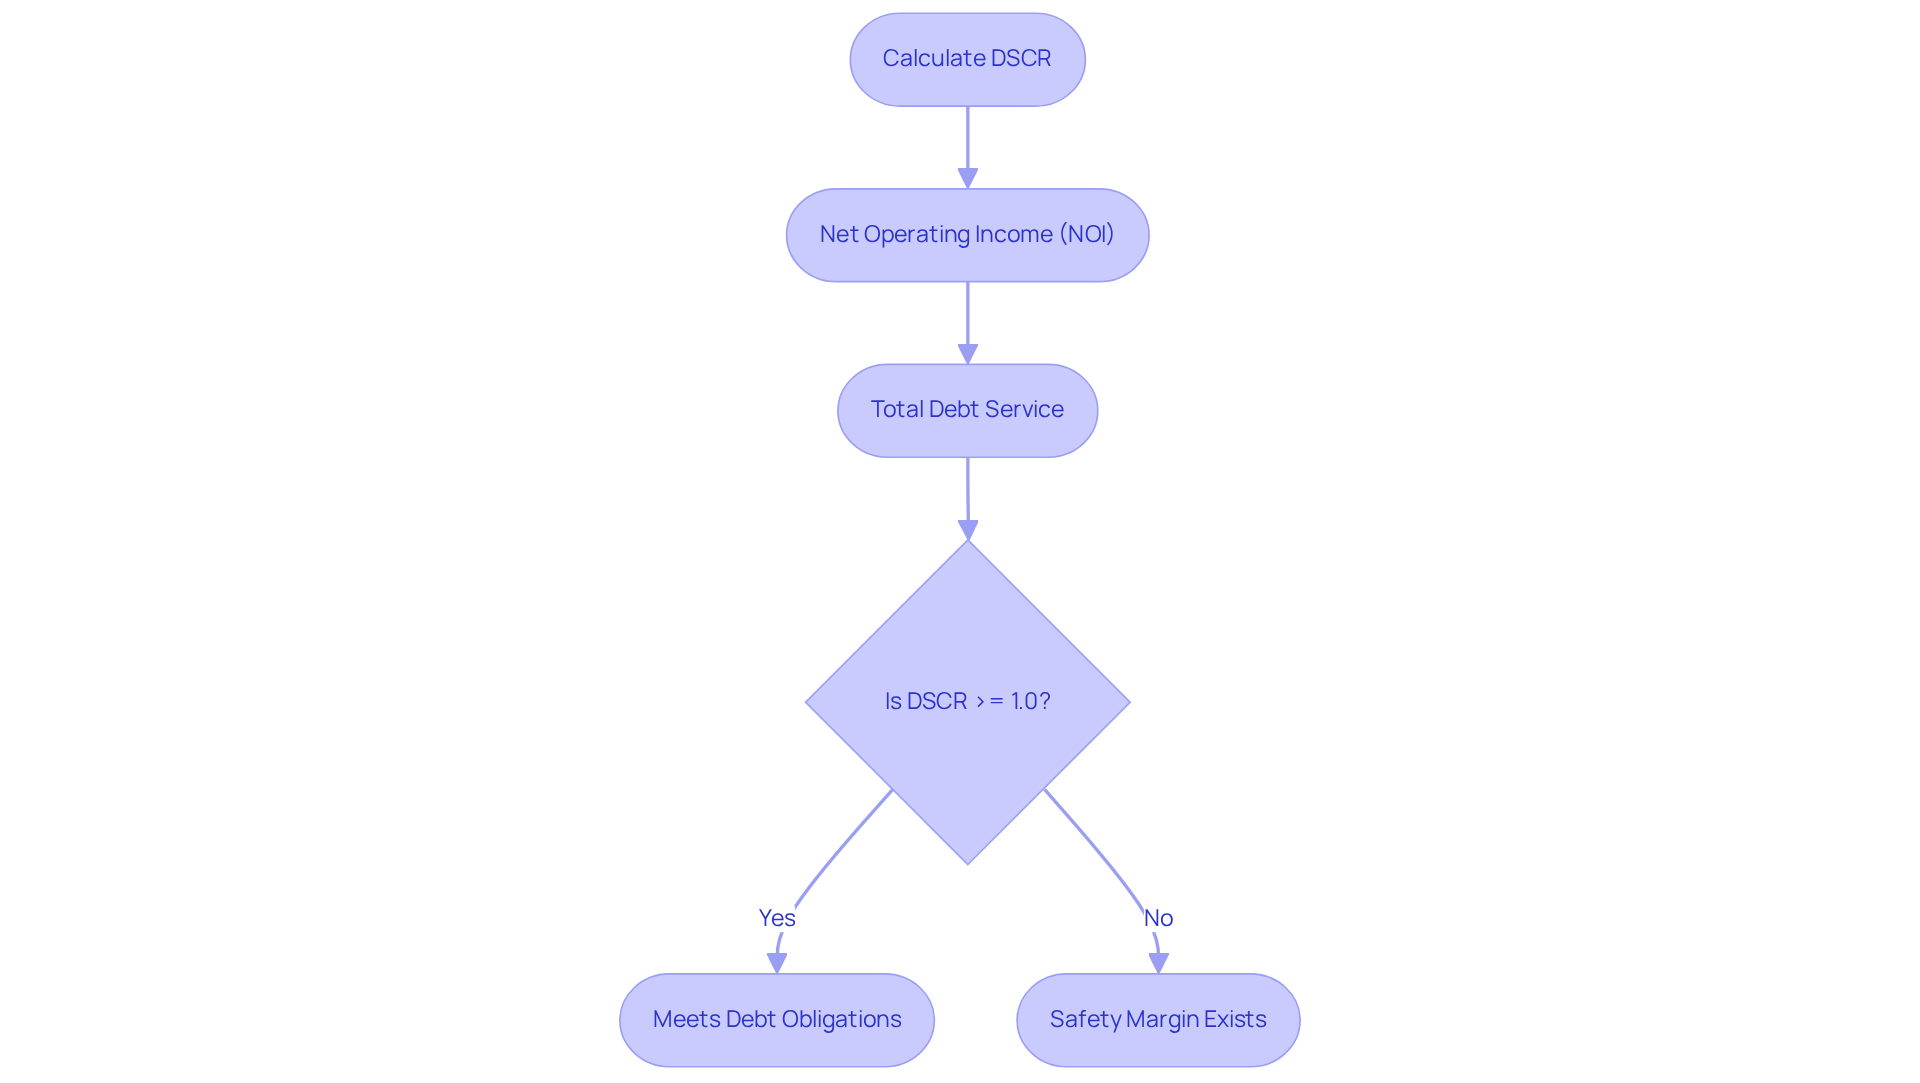
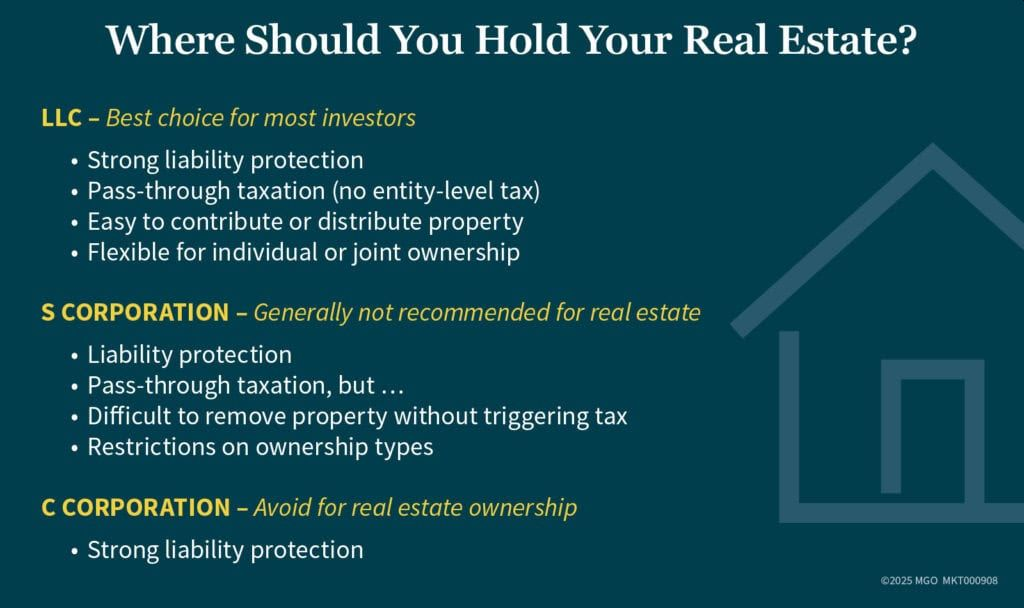
Maintaining the same LLC avoids triggering enhanced due diligence—or outright loan denial.
Best Practices for Maintaining LLC Continuity
1. Plan the Entity Before You Buy
Create one LLC designed to survive the full lifecycle of the deal, including long-term ownership if needed.
2. Maintain Clean Financial Records
Consistent bookkeeping inside the same LLC is one of the strongest refinance accelerators.
3. Keep All Contracts in the LLC Name
From purchase contracts to rehab invoices—everything should flow through the same entity.
4. Communicate Early with Lenders
Confirm entity expectations before closing, not at refinance.
Conclusion
Maintaining the same LLC for purchasing, rehabilitating, and refinancing is no longer just best practice—it’s increasingly a lender requirement.
LLC continuity:
- Speeds approvals
- Reduces legal friction
- Protects tax positioning
- Preserves refinance eligibility
As lender scrutiny intensifies heading into 2026, disciplined entity structure will separate successful investors from stalled deals.
For more real-world financing strategies, lender insights, and investor education, explore our resources and stay ahead of the curve.